News
Serious mortgage delinquencies tick up after five months of improvement.
After five months of improvement, more homeowners fell 90 days or more behind in August. Foreclosure growth slowed, but remains above last year.
What happened
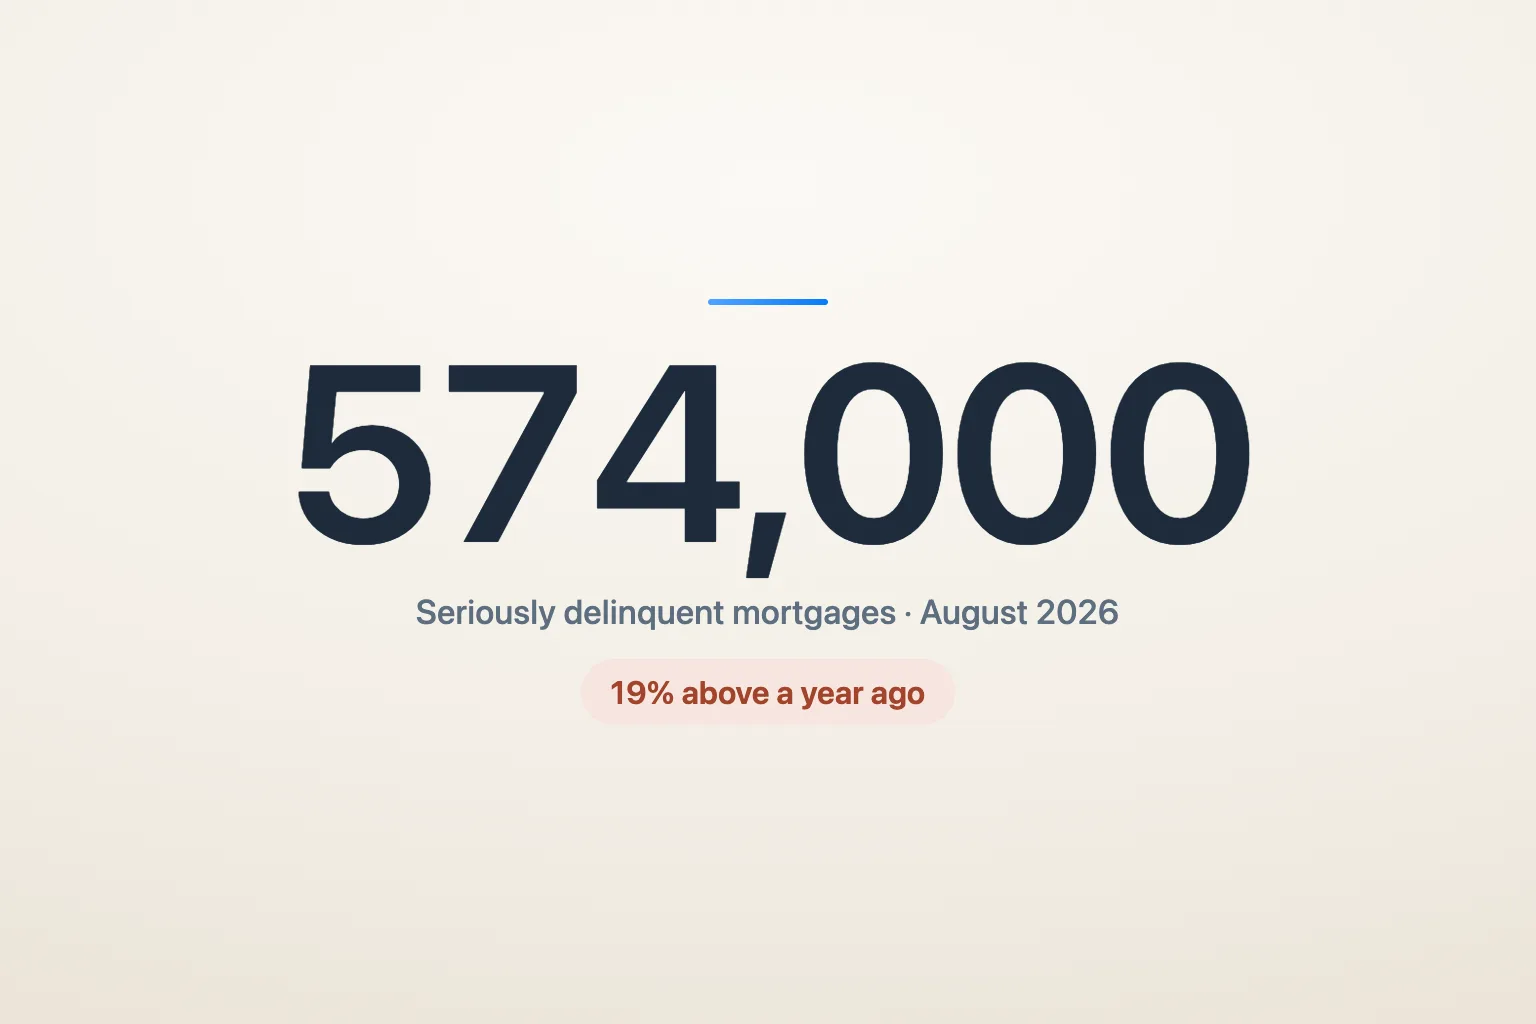
After five months of steady improvement, serious mortgage delinquencies, meaning loans that are 90 or more days past due but not yet in foreclosure, rose by 11,000 to 574,000 in August 2026, according to Intercontinental Exchange’s (ICE) August 2026 First Look report. That is 19% higher than a year earlier. The total represents 1.04% of all active mortgages, similar to the pre-pandemic average for August from 2017 to 2019.
The wider picture
The national delinquency rate, which includes all past-due loans, also rose slightly in August to 3.53%. However, this rate remains lower than pre-pandemic levels for the same month in prior years. While fewer borrowers are entering early stages of financial distress compared to last year, a significant number of homeowners are struggling with serious delinquencies.
Foreclosures
Foreclosure activity grew more slowly. Active foreclosure inventory rose by only 2,000 loans in August, the smallest monthly increase since November 2025. Foreclosure starts and inventory nonetheless remain well above last year’s levels.
What it means for homeowners
For homeowners, this data highlights the importance of staying proactive about mortgage payments and seeking assistance early if financial difficulties arise. Programs and resources may be available to help borrowers avoid serious delinquency or foreclosure.
Sources & further reading
- ICE: First Look at August 2026 Mortgage Data (September 28, 2026)
- Business Wire: ICE First Look, mortgage performance remains stable as foreclosure inventory growth slows (September 28, 2026)
General information, not advice about your circumstances. Read the original sources for their full definitions and context. Statistics describe the stated period, not a personal outcome.